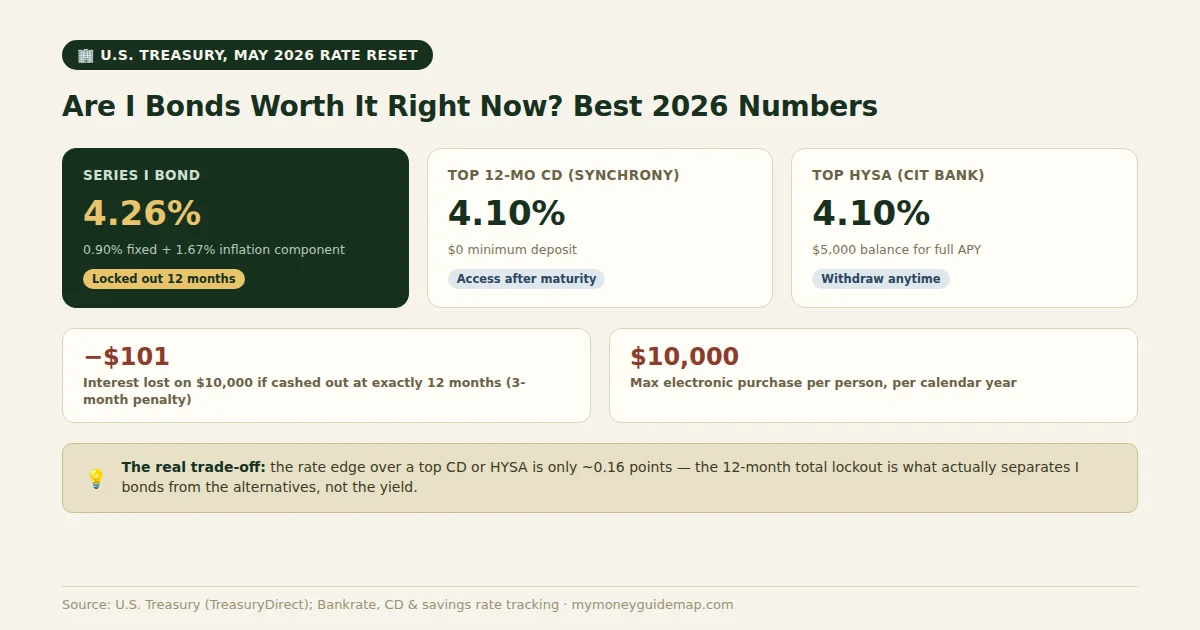
Are I bonds worth it right now, with a headline rate that beats almost everything else in savings? Series I savings bonds bought between May and October 2026 earn a 4.26% composite rate, according to the Treasury’s own rate announcement — made up of a 0.90% fixed rate locked in for as long as you hold the bond, plus a 1.67% inflation adjustment that resets every six months. On paper, that number alone puts I bonds ahead of nearly every CD and savings account available today.
Are I Bonds Worth It Right Now, Compared to a CD or HYSA?
Line the actual numbers up and the gap is smaller than it looks, but it’s real. A Series I bond bought this month earns 4.26% for its first six months. Synchrony Bank’s top 12-month CD is paying 4.10% with no minimum deposit, and CIT Bank’s high-yield savings account tops Bankrate’s own tracking at the same 4.10%. The I bond’s rate is genuinely higher — but only by 0.16 percentage points, and only until the inflation component resets in November based on wherever CPI lands next.
On $10,000, that rate difference is about $16 over a year — hardly enough on its own to answer are I bonds worth it right now for most savers. What actually separates these three options isn’t the rate at all; it’s how much of your own money you’re allowed to touch, and when.
The Catch: You Can’t Touch It for a Year
Are I bonds worth it right now if there’s any chance you’ll need the cash within a year? Not even close — I bonds come with a rule neither a CD nor a savings account has: you cannot redeem one at all for the first 12 months, full stop, regardless of the rate or your circumstances. A high-yield savings account never locks you out, and even a CD’s early-withdrawal penalty still lets you get the cash if you’re willing to give up some interest.
The lockup doesn’t end at 12 months, either — it just gets less punishing. Cash an I bond out anytime before you’ve held it 5 years and you forfeit the last 3 months of interest. Put a number on that: $10,000 in I bonds redeemed at exactly the 12-month mark effectively earns only about 9 months of interest once the penalty is applied, which works out closer to $325 instead of the full $426 the 4.26% rate implies — a roughly $101 haircut for cashing out at the earliest possible moment.
Who I Bonds Actually Make Sense For
Are I bonds worth it right now for a beginner’s emergency fund? No — the 12-month lockout alone rules that out, since an emergency fund needs to be reachable the moment something goes wrong, and a high-yield savings account or money market account is the right home for that money instead. The same logic applies to anything with a due date inside the next year or two: a wedding, a car you’re planning to buy, a move.
Where I bonds earn their place is money you’re genuinely comfortable not touching for at least a year, ideally closer to five — the down payment fund for a home purchase that’s still a few years out, or savings layered on top of an already-funded emergency fund. The interest is also exempt from state and local income tax, and federal tax can be deferred until you cash the bond or it matures, which is a real, if secondary, advantage over a CD or savings account where interest is taxed the year you earn it.
There’s also a practical limit worth knowing before getting excited about the rate: purchases are capped at $10,000 per person per calendar year through the electronic TreasuryDirect system, so I bonds work best as one piece of a savings plan rather than the whole thing.
So, are I bonds worth it right now? For money with no fixed deadline and no chance of being needed inside a year, yes — the rate edge over a top CD or HYSA is real, if modest, and the tax treatment sweetens it further. For anything you might need sooner, the same rate advantage disappears the moment the 12-month lockout stands between you and your own cash.